Mortgage Rates Today: Why They’re High, When They Could Fall & Why Waiting May Backfire (2026–2027)
August 28, 2026
August 28, 2026
Updated August 28, 2026
Mortgage rates remain one of the biggest obstacles facing homebuyers in 2026. Buyers keep asking the same understandable questions:
Why are mortgage rates still so high? Will they decline before the end of 2026? Will rates finally fall in 2027? Should I wait for a lower rate before buying a home?
Here is the direct answer: mortgage rates could fluctuate or temporarily move lower, but the latest major forecast does not predict a significant decline during the remainder of 2026 or in 2027.
The average 30-year fixed mortgage rate was 6.66% as of August 27, 2026. Fannie Mae’s August housing forecast projects that rates could average approximately 6.8% during the fourth quarter of 2026 and remain around 6.7% to 6.8% throughout 2027.
That forecast may prove wrong—mortgage-rate forecasts frequently change—but buyers should not build an entire home-purchase strategy around the assumption that rates will soon fall into the 5% range.
Waiting can be appropriate if the current payment is not affordable, your employment is uncertain, your savings are insufficient or you do not expect to remain in the home long enough. The potential mistake is waiting solely because you believe you can accurately predict mortgage rates.
According to the Freddie Mac Primary Mortgage Market Survey, national mortgage-rate averages as of August 27, 2026 were:
One year earlier, the average 30-year fixed rate was 6.56%. That means rates are slightly higher than they were at the same point in 2025.
Freddie Mac’s historical data also shows how much rates have changed during 2026. The average 30-year rate briefly dipped below 6% in late February before climbing through the spring and summer. It reached 6.66% by late August.
These are national averages, not guaranteed borrower rates. Your actual interest rate can be affected by your credit score, down payment, loan amount, property type, occupancy, debt-to-income ratio, points, lender and loan program.
Fannie Mae’s August 2026 housing forecast provides the following outlook for the average 30-year fixed mortgage:
Period | Fannie Mae forecast |
|---|---|
Third quarter of 2026 | 6.7% |
Fourth quarter of 2026 | 6.8% |
First quarter of 2027 | 6.8% |
Second quarter of 2027 | 6.8% |
Third quarter of 2027 | 6.7% |
Fourth quarter of 2027 | 6.7% |
Fannie Mae forecasts an average rate of 6.5% for all of 2026 and 6.7% for 2027.
The important takeaway is not that rates will land on these exact numbers. The takeaway is that one of the nation’s major housing forecasters does not currently expect a dramatic rate decline.
Forecasts can change quickly when inflation, employment, economic growth, government policy or global events surprise financial markets. Buyers should therefore treat forecasts as planning tools—not promises.
Mortgage rates are high because investors continue demanding substantial returns to hold long-term bonds and mortgage-backed securities.
Several forces are contributing to the current environment.
Inflation is one of the most important influences on long-term interest rates.
A lender or bond investor receiving fixed payments for decades loses purchasing power when inflation remains elevated. Investors generally demand a higher interest rate to compensate for that risk.
The Federal Reserve’s preferred inflation measurement is the Personal Consumption Expenditures price index. According to the Bureau of Economic Analysis, the PCE price index was 3.7% higher in July 2026 than one year earlier. Core PCE, which excludes food and energy, was up 3.3%.
The Federal Reserve’s longer-term inflation goal is 2%. Until inflation moves convincingly and sustainably closer to that target, long-term rates may have difficulty falling significantly.
The Federal Reserve does not directly set 30-year mortgage rates.
The Fed controls a target range for the federal funds rate, which applies to overnight lending between banks. At its July 2026 meeting, the Federal Open Market Committee maintained that target at 3.50% to 3.75%.
Thirty-year fixed mortgages are long-term financial instruments. Their pricing follows longer-term bond yields—particularly Treasury securities and mortgage-backed securities—more closely than the overnight federal funds rate.
On August 27, 2026, the 10-year Treasury yield was approximately 4.67%. The average 30-year mortgage rate was 6.66%, creating a difference of approximately two percentage points.
Mortgage rates can remain high even when the Fed stops raising its short-term rate because long-term investors may still be concerned about inflation, economic growth, federal borrowing or future policy.
High mortgage rates are not always a sign that the economy is performing poorly. They can remain elevated because the economy is stronger than expected.
In its July statement, the Federal Reserve said economic activity continued expanding at a solid pace, job gains had kept pace with the workforce and unemployment had changed little.
A strong economy can keep rates elevated because:
Mortgage rates often fall most sharply when markets become worried about recession, unemployment or financial instability. Lower rates can therefore arrive alongside economic conditions that are not necessarily favorable for every buyer.
Most conventional mortgages are packaged into mortgage-backed securities and sold to investors. Investors evaluate interest-rate risk, prepayment risk and market volatility before deciding what return they require.
Mortgage borrowers can refinance when rates fall. That means investors may lose a higher-yielding mortgage sooner than expected. When rates rise, borrowers are less likely to refinance, leaving investors holding lower-yielding securities for longer.
That unusual combination of risks is one reason mortgage rates normally sit above comparable Treasury yields. Research from the Federal Reserve Bank of New York explains how mortgage-backed-security spreads affect homeowners’ borrowing costs.
Global conflict and disruptions to energy markets can raise fuel, transportation and production costs. If investors believe those costs will create renewed inflation, they may demand higher Treasury and mortgage yields.
The Federal Reserve’s July statement specifically noted that inflation remained elevated partly because of supply shocks affecting sectors such as energy.
Geopolitical events can affect rates in competing ways. A flight toward the relative safety of Treasury securities can push yields down, while an energy shock that increases inflation expectations can push yields up. The final effect depends on which concern dominates the market.
Mortgage rates would be more likely to fall if several of the following conditions developed:
One favorable monthly report is rarely enough. Investors generally want to see a sustained pattern of lower inflation before accepting lower long-term yields.
Slower consumer spending, weaker business activity or declining confidence can reduce inflation pressure and encourage investors to purchase bonds. Increased bond demand normally pushes yields lower.
A meaningful rise in unemployment or a sustained slowdown in job growth could lead markets to expect easier Federal Reserve policy and weaker inflation.
A Fed rate cut can help mortgage rates, but it does not guarantee they will fall.
If the Fed cuts because inflation is clearly improving, long-term yields may decline. If it cuts while investors remain worried about inflation, the 10-year Treasury and mortgage rates could remain elevated—or even rise.
Mortgage rates could fall even without a large Treasury-yield decline if investors require less additional compensation to hold mortgage-backed securities.
During periods of serious economic concern, investors often move money into Treasury securities. That can push long-term yields and mortgage rates lower, although it may also create employment or income risks for potential buyers.
Mortgage rates could move above current levels if:
Rates can also change before the Federal Reserve makes an announcement. Financial markets constantly price in what investors believe the Fed will do months or years in the future.
They could decline temporarily, but the latest Fannie Mae forecast does not expect a lasting decrease before year-end.
Fannie Mae projects the average 30-year rate rising from approximately 6.7% in the third quarter to 6.8% in the fourth quarter.
That does not mean every week will be higher. Mortgage rates can move several times during a single week as investors react to inflation reports, employment data, Treasury auctions, Federal Reserve comments and international developments.
A buyer may encounter a brief rate-locking opportunity even if the quarterly average remains high. This is why a prepared buyer working with a responsive lender can have an advantage over someone who waits for a widely publicized rate decline.
Fannie Mae currently expects rates to remain approximately where they are.
Its August forecast calls for a 6.8% average during the first half of 2027 and 6.7% during the second half. That would be stability, not a meaningful affordability breakthrough.
Could rates fall below that forecast? Absolutely. A faster decline in inflation or a significant economic slowdown could bring rates down.
Could they rise instead? Yes. Persistent inflation, stronger economic growth or a wider mortgage-bond spread could keep rates higher.
The honest answer is that nobody can reliably predict an individual mortgage rate one year in advance. Buyers should plan using a range of possible outcomes rather than one perfect number.
Waiting is not automatically wrong. Waiting solely because you are certain rates will fall can be.
Here are the primary risks.
The most obvious risk is that the expected decline never arrives.
A buyer who postponed purchasing in February 2026, when the national average briefly fell below 6%, faced an average of 6.66% by late August. Markets do not always move in the direction consumers expect.
The current Fannie Mae forecast does not show a sub-6% average at any point through the end of 2027.
If rates fall meaningfully, purchasing power improves for a large number of buyers at the same time.
That can create:
A lower rate is helpful, but not if increased competition forces a buyer to pay substantially more or waive important protections.
This outcome is not guaranteed. Local inventory, home prices and buyer demand will determine what happens in each Sonoma County neighborhood.
Consider a hypothetical $700,000 home with 20% down.
At a 6.66% rate, the $560,000 loan would have an estimated principal-and-interest payment of approximately $3,599 per month.
Now assume the buyer waits, the mortgage rate falls to 6%, but the home’s price rises 5% to $735,000. With 20% down, the new $588,000 loan would produce an estimated payment of approximately $3,525.
The buyer waited for a 0.66-percentage-point rate reduction but saved only about $74 per month on principal and interest. The purchase price increased by $35,000, and the required 20% down payment increased by $7,000.
This is only an illustration. Prices could rise, fall or remain flat. It demonstrates why buyers must evaluate the rate and purchase price together.
Real estate is not a uniform investment purchased from an unlimited supply.
A particular neighborhood, street, floor plan, lot or property condition may be difficult to duplicate. Waiting for a rate target can mean losing a home that fits your longer-term needs.
That does not mean overpaying or forcing a purchase. It means the quality and suitability of the property should be considered alongside the financing.
Mortgage rates could decline because unemployment rises or economic conditions deteriorate. A buyer waiting for lower rates may discover that qualifying is harder if income, employment or financial confidence changes.
The ideal scenario—lower rates, lower prices, abundant inventory and strong personal finances—does not always arrive at the same time.
A buyer who purchases with a fixed-rate mortgage has protection if rates rise: the principal-and-interest payment remains fixed.
If rates later decline enough, refinancing may provide an opportunity to reduce the payment. However, refinancing is not automatic. It can involve closing costs, underwriting, an appraisal and qualification based on the borrower’s future credit, income, equity and property value.
Buyers should purchase only when the current payment is comfortable. A future refinance should be treated as possible upside—not as the plan required to make the home affordable.
For a longer historical perspective, read my guide to historical mortgage rates and what they mean for Sonoma County buyers.
Instead of trying to predict the exact bottom, buyers can focus on the parts of the transaction they can control.
Calculate a payment that works with your actual income, savings, insurance estimate, taxes, HOA dues, maintenance and other obligations.
The lowest advertised rate is not necessarily the least expensive loan. Compare the interest rate, annual percentage rate, points, lender fees, mortgage insurance and cash required at closing.
Reducing revolving debt, correcting credit-report errors, protecting your credit score and increasing the down payment may improve the rate available to you.
A seller credit may be used toward allowable closing costs or an interest-rate buydown, subject to loan-program rules. In some situations, a credit can improve the buyer’s immediate affordability more effectively than a similar reduction in purchase price.
Purchase price matters, but so do repairs, credits, included property, contingency protections, closing date and other terms.
A prepared buyer can respond when rates temporarily improve. Ask the lender about lock periods, extension costs, float-down options and what events could change the quoted rate.
Sellers should understand that buyers shop according to monthly payment, not simply purchase price.
At today’s rates, an overpriced home can become unaffordable quickly. Strategic pricing may attract more buyers and produce a stronger overall result than beginning too high and reducing the price after the listing becomes stale.
Depending on the property and offer, a seller may also evaluate:
The best option depends on the seller’s proceeds, the buyer’s loan program and the property’s competitive position.
Mortgage rates also contribute to the homeowner “lock-in effect.” Many owners with older, lower-rate mortgages hesitate to sell and replace them with a higher-rate loan. That can limit inventory and help support prices in certain Sonoma County markets. My analysis of whether Sonoma County home prices could decline in 2026 examines that issue in greater detail.
No. The Federal Reserve sets a target range for the overnight federal funds rate. Mortgage rates are influenced more directly by longer-term bond yields, mortgage-backed securities, inflation expectations and investor demand. Fed policy still matters because it affects the broader economy and expectations for future rates.
It is possible, but the latest Fannie Mae forecast does not predict it. Its August 2026 outlook projects an average 30-year rate of 6.8% during the fourth quarter.
Fannie Mae currently projects rates averaging 6.8% during the first half of 2027 and 6.7% during the second half. That would not represent a significant decline from current levels.
Wait if the current payment is unaffordable or buying does not fit your financial and personal plans. Do not wait solely because you assume rates will be materially lower next year. Compare the payment, property, price, competition and likely ownership period together.
That can work, but refinancing is never guaranteed. Buy only if the current payment is manageable. Treat a future refinance as an opportunity rather than a requirement.
The impact depends on the loan amount. On a $560,000 30-year loan, reducing the rate from approximately 6.66% to 5.66% would lower principal and interest by roughly $330 per month. Taxes, insurance and HOA dues would not decrease because of the refinance.
Not necessarily. Advertised rates may assume specific credit scores, down payments, loan amounts, points and property types. Obtain a personalized Loan Estimate and compare the total cost.
Mortgage rates are near the mid-to-upper 6% range because inflation remains above the Federal Reserve’s goal, long-term Treasury yields are elevated and investors continue requiring additional compensation to hold mortgage-backed securities.
Rates could decline if inflation cools, the economy slows or bond-market conditions improve. They could increase if inflation accelerates, growth remains strong, energy pressures persist or investors demand higher long-term returns.
The latest major forecast does not show meaningful relief during the remainder of 2026 or in 2027.
For Sonoma County buyers, the better question is not, “Can I predict the lowest mortgage rate?”
It is, “Can I purchase the right home with a payment I can comfortably afford today?”
If the answer is yes, waiting for a perfect rate could mean facing a higher price, more competition or losing the right property. If the answer is no, the correct strategy is to improve your finances and prepare—not gamble on a forecast.
If you are considering buying or selling a home in Santa Rosa, Rohnert Park, Petaluma, Cotati, Windsor or elsewhere in Sonoma County, I can help you compare current properties, estimated payments and negotiation strategies.
Visit Nima.Homes or call or text me at 707-486-9055 to discuss your real-estate plans.
Nima Kazeroonian
Broker Associate, Coldwell Banker Realty
California DRE License #01491305
Discover what it is like to live in Rohnert Park’s M Section, including its homes, Magnolia Park, nearby schools, location, parking rules and current real estate consi… Read more
Mortgage rates may remain elevated after the Fed’s September 2026 rate increase, but correctly priced homes in Santa Rosa, Rohnert Park, Petaluma, Windsor, Cotati, and… Read more
Explore K Section’s location, Twin Creeks Park, nearby Sonoma State and the ownership costs to understand before buying.
A local look at M Section housing, Magnolia Park, nearby schools, current prices and what Rohnert Park buyers and sellers should know.
An updated look at today’s mortgage rates, the economic forces controlling them, what forecasters expect through 2027 and why timing the market may cost Sonoma County … Read more
A local comparison of 2026 home prices, housing choices, neighborhoods, commute options, schools and everyday lifestyle across three popular Sonoma County communities.
A City-by-City Guide to Houses, Condos and Townhomes Under $700K in Santa Rosa, Rohnert Park, Cloverdale, Cotati, Windsor and the Russian River
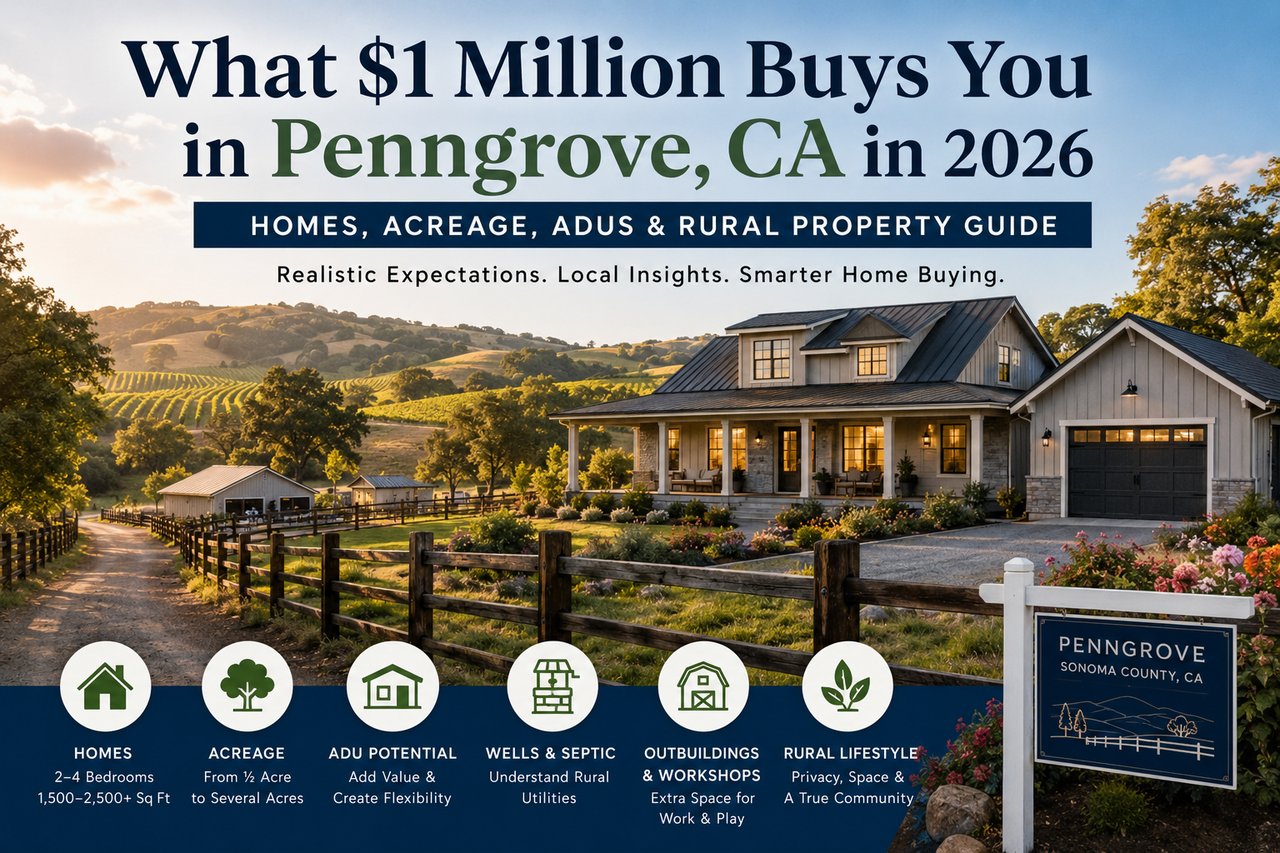
A Local Guide to Penngrove Real Estate Around $1 Million — Including Home Sizes, Acreage, ADU Potential, Wells, Septic Systems and What Buyers Should Expect Before Mak… Read more
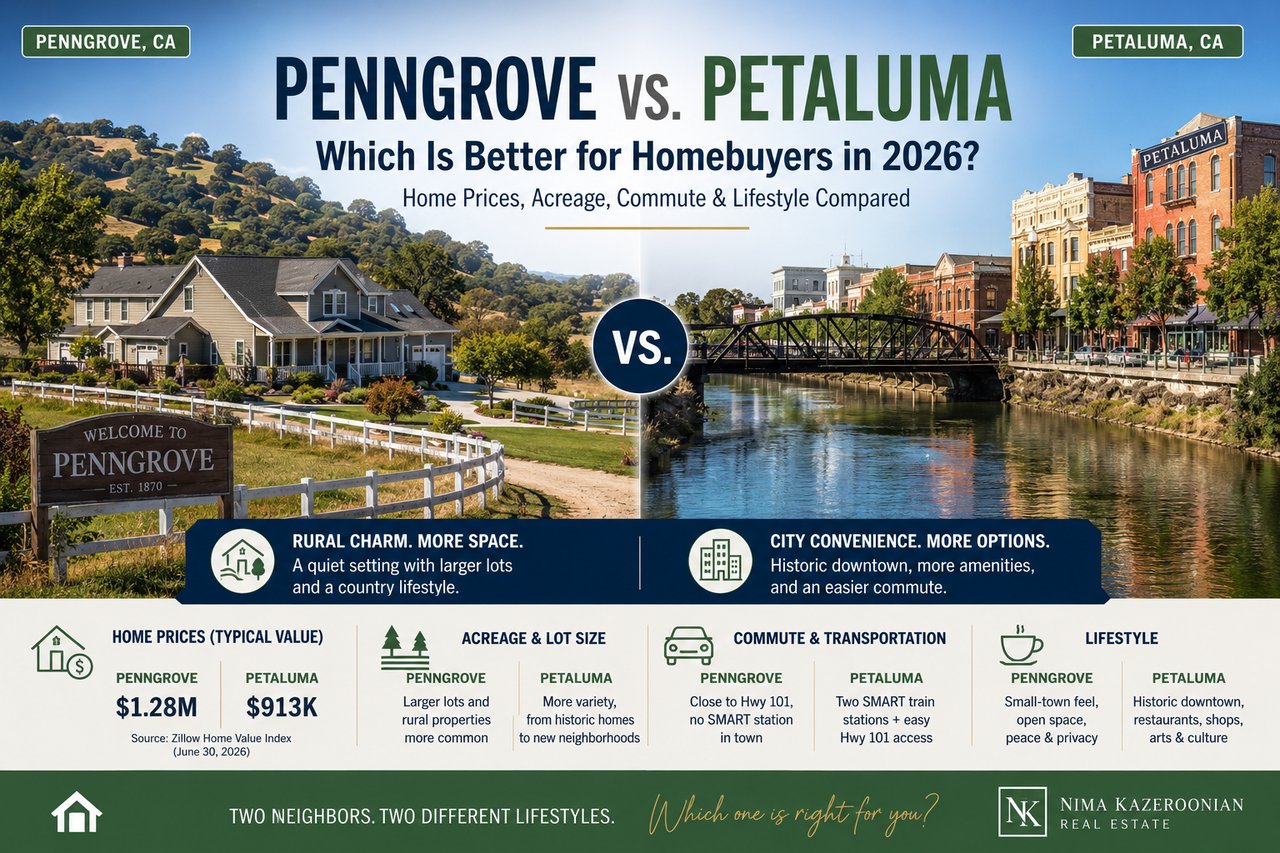
Penngrove offers more of the rural Sonoma County experience and larger-property opportunities, while Petaluma gives buyers a larger housing market, historic downtown, … Read more
Whether you're buying, selling, or exploring options, Nima is dedicated to making the process smooth, informed, and rewarding. Reach out today for a personalized consultation and let’s make your real estate goals a reality!