The Truth About Rising Home Insurance Costs in Sonoma County — What’s Really Happening & How Homeowners Can Lower Their Premiums
Nima Kazeroonian November 26, 2025
Nima Kazeroonian November 26, 2025
If you own a home in Sonoma County, you’ve probably felt the sting of rising insurance premiums. Rates have climbed sharply over the last five years—especially in areas labeled “high fire-risk zones.” But the story behind these increases is more complex than simple risk scoring. State regulations, carrier exits, wildfire modeling, and new mitigation rules all play a part.
Here’s what homeowners need to know right now—and the steps that can actually reduce insurance costs in 2025–2026.
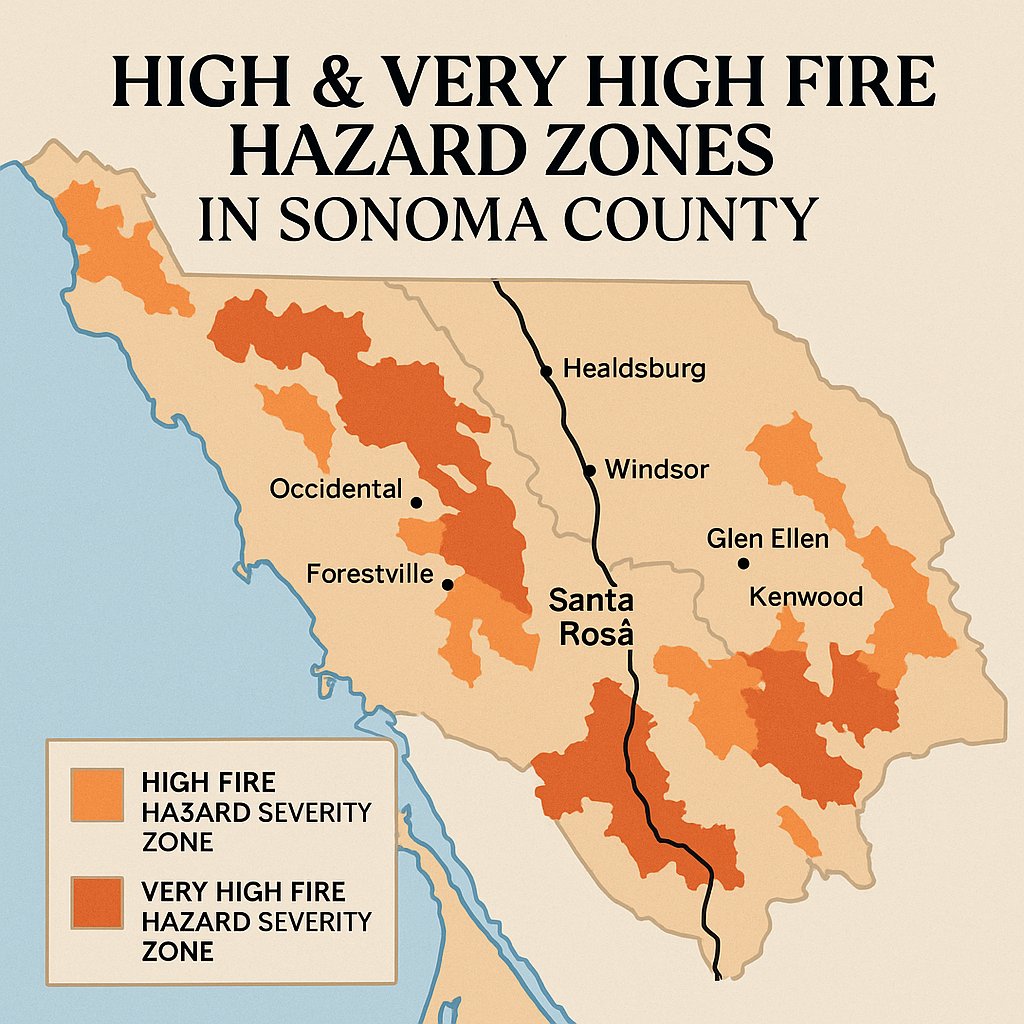
Large portions of Sonoma County fall into CalFire’s “High” or “Very High” Fire Hazard Severity Zones—especially in:
Santa Rosa (Fountaingrove, Bennett Valley, Montecito Heights)
Healdsburg
Windsor foothills
Glen Ellen, Kenwood
West County (Occidental, Forestville, Guerneville)
When a home is inside these zones, insurers apply higher premiums due to increased wildfire exposure.
Over the last few years, several carriers paused new policies or tightened underwriting. Why?
Higher wildfire losses
Reinsurance costs skyrocketing
State regulations limiting rate increases
Carriers shifting away from rural/wildland-urban interface areas
Some insurers are gradually returning, but under stricter conditions—and often tied to mitigation improvements.
Insurers now use more detailed wildfire-risk models that evaluate:
Slope and topography
Distance to open wildland
Wind patterns
Evacuation access
Neighborhood vegetation density
Two homes on the same street can get completely different quotes based on these factors.
This is one of the top factors insurers look at. Key actions include:
Removing brush and ladder fuels
Trimming tree limbs 6–10 ft off the ground
Clearing roofs and gutters
Replacing mulch near structures with gravel
Some carriers reduce premiums after you provide before/after photos.
Upgrades that make a major difference:
Class A fire-rated roof
Stucco, cement board, or ignition-resistant siding
Ember-resistant vents
Dual-pane tempered windows
5-feet non-combustible zone around the home
These improvements can push your property into a better risk tier.
Insurers want to see:
Hydrants within 1,000 feet
Clear driveway access
Room for fire truck turnaround
In rural areas, adding a permitted water storage tank can help with eligibility.
If your neighborhood participates in Firewise, some insurers offer discounts up to 10%.
Slowly—yes.
As California’s new insurance regulations roll out, several carriers have signaled they will re-enter the market. But expect:
Tight underwriting
More documentation
Required mitigation for older homes
Premiums won’t drop overnight, but competition will gradually improve.
Work with brokers who can access:
Surplus lines carriers
Regional insurers
High-risk programs
Some can beat FAIR Plan pricing depending on your zip code.
Bundling home and auto can save 10–20%.
Increasing from $1,000 to $2,500 can meaningfully reduce premiums.
Many carriers now allow inspections that confirm:
Defensible space
Hardened features
Ember-resistant venting
Roofing materials
Passing can drop your premium immediately.
Most homeowners overpay simply because they stay with the same policy for too long. Rates shift constantly—especially in Sonoma County.
Insurance rates are high—and fire-zone mapping is a big driver—but homeowners have more control than they think. Strategic mitigation, home-hardening, bundling, and yearly reviews can lead to real savings. And as insurers slowly return to the California market, options should expand in 2025–2026.
If you want help understanding how insurance changes impact your property’s value, marketability, or selling strategy, I’m always here to walk you through it.
A practical guide to down payments, closing costs, mortgage payments, and assistance options for Santa Rosa and Sonoma County homebuyers.
From M Section to University District, compare taxes, HOA fees, insurance and repairs before choosing your next home.
An October–December 2026 forecast for all nine cities, how local home values compare with California counties, and why Sonoma County remains a compelling place to live.
Before you remodel, learn which updates may not pay off, what buyers notice, and which repairs deserve attention before listing.
How assumable mortgages work, what they could save, and the upfront cash requirement that can change the entire deal.
The national 30-year average reached 7.03% on September 24. Here is what that changes for payments, pricing, negotiations, and home sales in Santa Rosa and across Sono… Read more
Discover what it is like to live in Rohnert Park’s M Section, including its homes, Magnolia Park, nearby schools, location, parking rules and current real estate consi… Read more
Mortgage rates may remain elevated after the Fed’s September 2026 rate increase, but correctly priced homes in Santa Rosa, Rohnert Park, Petaluma, Windsor, Cotati, and… Read more
Explore K Section’s location, Twin Creeks Park, nearby Sonoma State and the ownership costs to understand before buying.
Whether you're buying, selling, or exploring options, Nima is dedicated to making the process smooth, informed, and rewarding. Reach out today for a personalized consultation and let’s make your real estate goals a reality!